Most Americans reaching age 65 will enroll in Medicare, the federal social insurance program for people age 65+ and people with certain disabilities. The program is funded primarily through your payroll taxes and premiums and is not a public assistance or government aid program.
Even if you’re not quite 65, it’s important to start planning your enrollment long before that milestone birthday in order to review the sometimes confusing options (Part A, Part B, Part D, Advantage plans), choose providers, learn what the plans cover and be prepared for what they’ll cost you.
Your personal Medicare enrollment window begins about three months before your 65th birthday month and lasts until three months after and sign-ups are through the Social Security Administration. Pay attention to these dates as missing your enrollment window can lead to gaps in coverage and late penalties.
Plans change every year so always check the Medicare website and your insurer for the latest information and be ready to change plans if necessary during open enrollment from October to December. Here’s a quick rundown of the Medicare numbers and what you need to know as of June 2026:
Part A
Medicare Part A, or “Original Medicare” covers hospital-related care, hospital stays, skilled nursing facility care (short-term), hospice care and limited home health services after a hospital stay.
While most people qualify for Part A at age 65, eligibility is based on work history, not income. You can get premium (free) Part A if you or your spouse worked and paid Medicare taxes for 40 quarters (about 10 years). But note, you’ll likely still have to pay deductibles and/or coinsurance including for hospital stays (more than $1,700 in 2026), daily hospital costs of $434 after 60 days and daily nursing home coinsurance of $217 after 20 days.
If you don’t meet the work requirement, you’ll likely have to pay a premium. If you’re unsure whether you’ve worked the 40 quarters at jobs in which you paid Medicare taxes, check your (and your spouse’s) work credits on the Social Security website, where you’ll also sign up for Medicare. Most people sign up for Part A at age 65 even if they have existing coverage through a job or spouse because it’s premium-free.
Part B
Medicare Part B covers medical costs such as doctor visits, outpatient care, screenings and labs, some medical equipment and limited home health services — basically the care you’ll receive outside a hospital or nursing home stay. Unlike Part A premiums, Part B for most people is not free. The standard monthly premium in 2026 for recipients who earn $109,000 or less is about $202.90. The premiums increase for higher earners. You’ll also pay an annual deductible — $283 in 2026 (be on the lookout for changes to the Part B deductible usually announced by the Centers for Medicare & Medicaid Services in the fall), and a copay of 20% of approved costs for most services after the deductible. For most people receiving Social Security, the monthly premium will be deducted directly from your Social Security check, otherwise you’ll have to pay a separate Medicare bill.
If you’re still working at age 65 and have coverage through your job or your spouse’s employer, you may be able to delay Part B without penalty, but it’s important to check the requirements.
Part C – Medicare Advantage
Medicare Advantage (Part C) plans are private insurance alternatives to Original Medicare that bundle hospital (Part A), medical (Part B), and often prescription drug coverage (Part D) into a single plan. According to a 2026 analysis by the Kaiser Family Foundation, a health policy research, polling and news nonprofit, these plans are widely chosen because they often feature low monthly premiums — sometimes as low as $0 beyond the standard Medicare Part B premium of about $202.90 per month — and include an annual cap on out-of-pocket medical costs, which averages about $5,421 for in-network services in 2026. Many plans also offer extra benefits not covered by Original Medicare, such as dental, vision, hearing and fitness programs. However, these advantages come with tradeoffs like restrictions on provider networks, prior authorizations and potential higher costs for out-of-network care.
Part D
Medicare Part D is optional private insurance you can purchase (about $34.50 per month in 2026, according to the Centers for Medicare & Medicaid) to help cover the cost of prescription drugs, most vaccines and medications to treat chronic conditions. The costs of Part D premiums, the copays or deductibles, and the covered drugs vary from provider to provider. It’s important to sign up for Part D even if you don’t take any or many medications or you may face a permanent late-enrollment penalty, unless you have other creditable drug coverage such as an employer or spouse’s employer’s coverage, retiree drug plan or VA or military drug coverage. In that case, Part D may be delayed.
Medicaid
Medicaid is a joint federal and state health insurance program that provides coverage for people with limited income and resources. Unlike Medicare (which is age-based), Medicaid is primarily income-based. It is administered by the state but funded jointly by the state and federal government. In many cases, seniors on Medicare qualify for Medicaid if their income and savings are limited.
Coverage varies by state, but Medicaid typically pays for most of what Medicare Part A, Part B and Part D cover, including some home and community-based services. There is little or no monthly premium, low or no copays and minimal out-of-pocket costs. Some people qualify for dual coverage by both Medicare and Medicaid, in which case Medicaid acts as a secondary payer covering many of the costs which remain after Medicare has paid.
Ways to Save: Medicare Savings Programs
There are several programs for income-eligible beneficiaries that may cover the costs of premiums, deductibles, coinsurance and/or copays. These programs put a limit on income and resources (assets) such as real estate (other than your primary residence), bank accounts, investments and cash:
- The Qualified Medicare Beneficiary Program for individuals earning $1,350 monthly (married couples $1,824), helps pay for Part A premiums (if you don’t have premium-free Part A); Part B premiums, deductibles, coinsurance and copays (for services and items Medicare covers).
- The Qualifying Individual Program is available for people who earn up to $1,816 monthly ($2,455 for a married couple) and only assists with payment of Part B premiums. Application for assistance from this program must be submitted annually. Funding is limited, and priority is given to those who received assistance from the program during the prior year.
- The Qualified Disabled and Working Individuals Program is designed for people under age 65 who have some disability but are employed. Monthly income must be less than $5,405 ($7,299 for a married couple). Assistance from this program is only available to cover the cost of Part A premiums.
Part D Extra Help Program
This federal program is administered through the Social Security Administration and helps with Part D premiums and drug costs. Estimated to be worth about $5,700 per year, many people are eligible for these big savings and don’t know it, the SSA writes in its 2026 guide to the program. To be eligible for Extra Help, your annual income must be limited to $23,475 ($31,725 for a married couple).
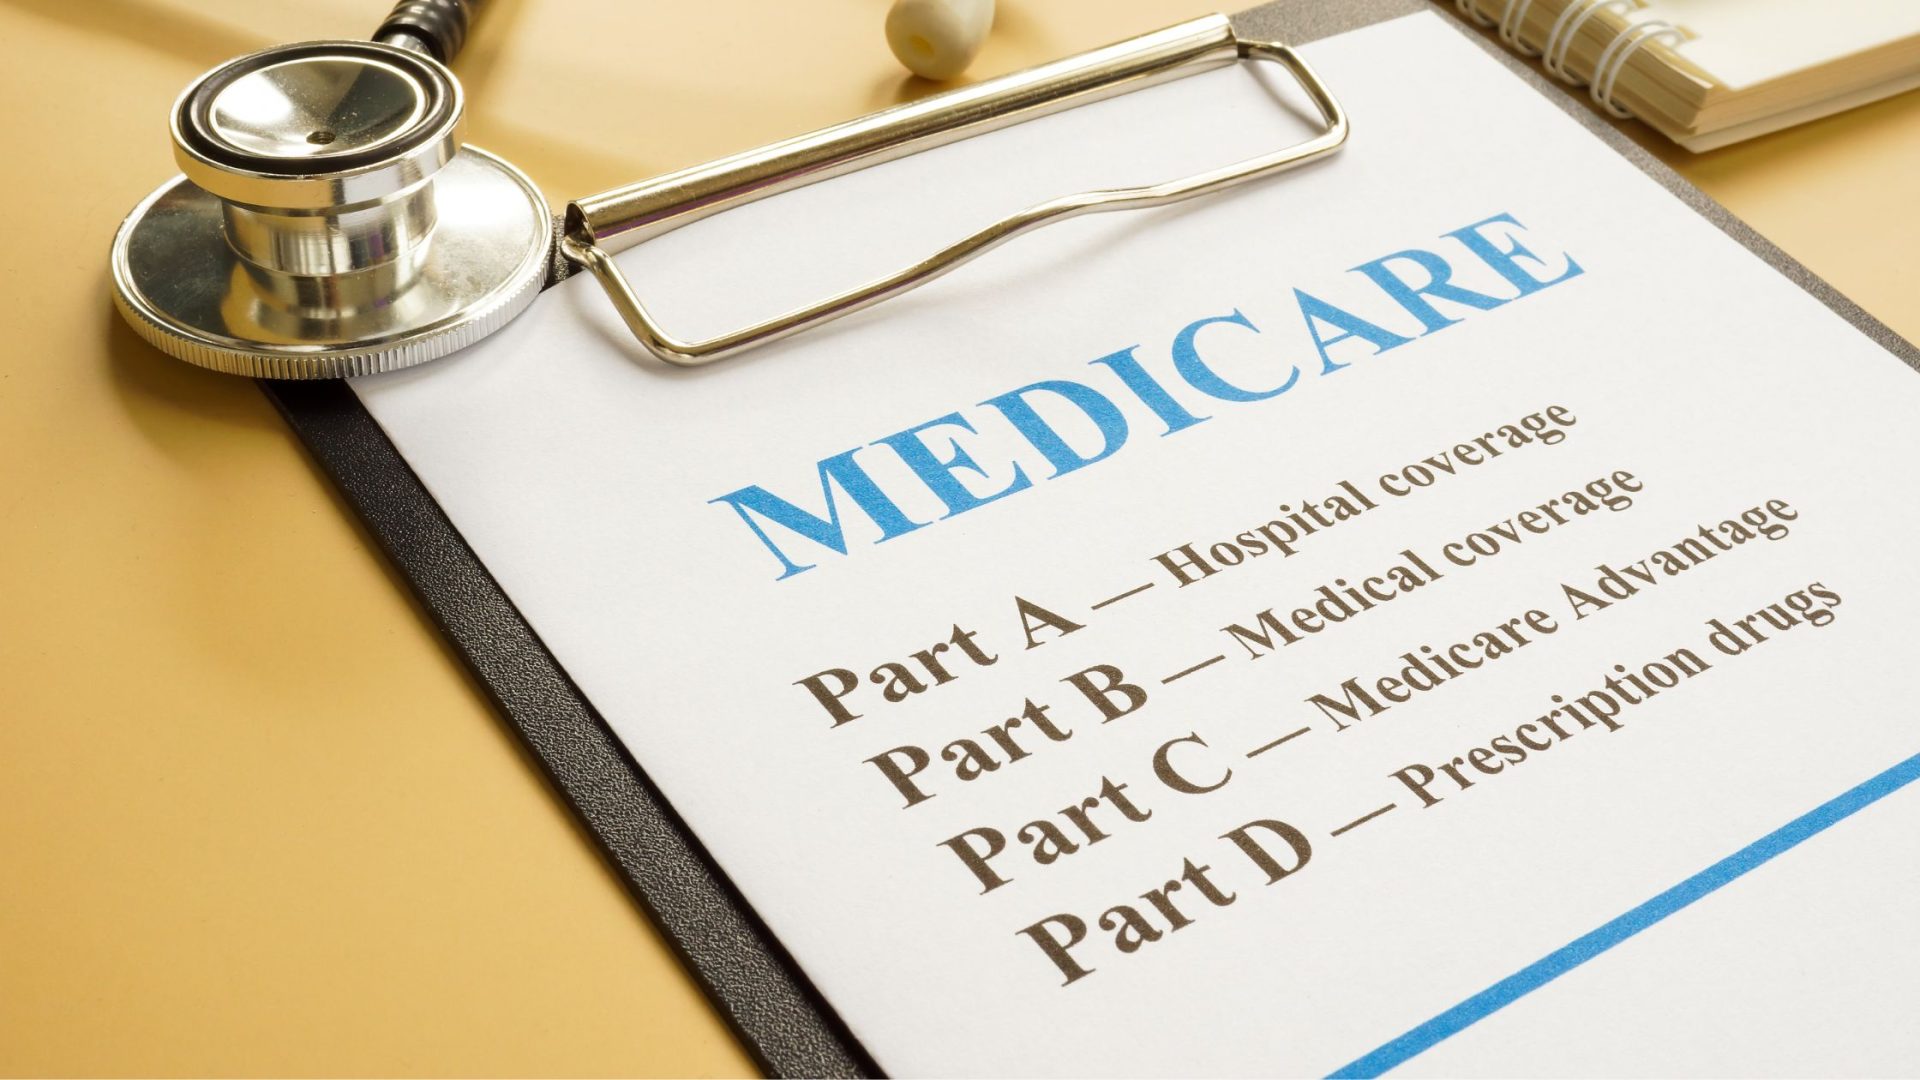
*Featured image courtesy of Designer 491 via Canva
*This article has been updated
READ MORE:
- Long-term care: the retirement wild card no one wants to discuss
- Your 2026 Retirement Playbook
- The 5 Best Places to Retire Overseas